


Key Events This Week: Jobs, Core PCE And ISM
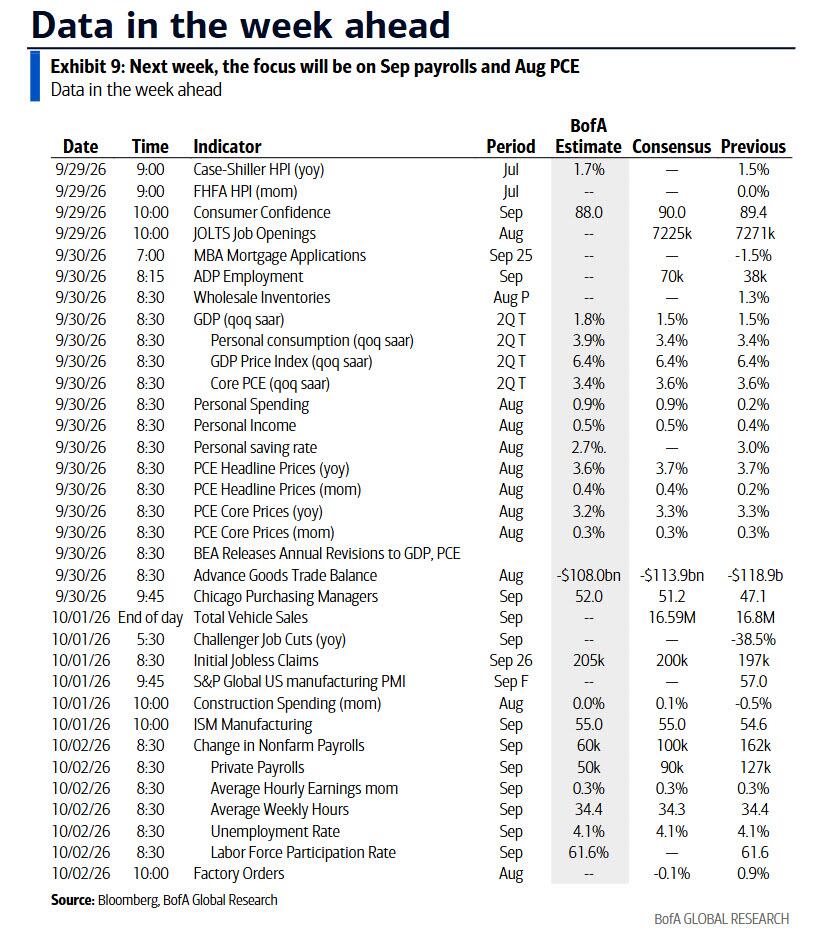
It's very busy week ahead with US payrolls (Friday) and PCE (Wednesday) as the blockbuster releases. The US ISM (Thursday) will attract outsized attention given the spectacular beat on the S&P PMI last week that sent 10yr US yields +15.2bps higher on the day. A huge move for such a report.
Global inflation will also be in focus outside of the US August PCE report with flash September CPI releases across Europe (Tuesday/Wednesday) and Tokyo CPI (Friday) all due. In Asia, investors will also be watching Chinese PMIs (Wednesday), the BoJ’s Tankan survey and summary of opinions (Thursday), as well as the RBA decision (tomorrow) where the market prices in a 93% probability of a hike. All that around month and quarter end on Wednesday.
In the US, attention will increasingly turn towards Friday’s September payrolls report. Following August’s stronger-than-expected gain of 162k, DB economists expect payrolls to rise by around 45k in September (Friday), with the unemployment rate unchanged at 4.1% and average hourly earnings growth steady at +0.3% month-on-month. Recent labor market indicators have remained reasonably firm, although some moderation after August’s strength would be consistent with a labou market that is cooling only gradually.
Ahead of Friday’s payrolls release, labor market data will begin arriving tomorrow with the August JOLTS report, before the September ADP employment release on Wednesday and weekly jobless claims on Thursday. Together, these releases should help shape last minute expectations going into the official employment report. Note that last week saw claims at 197k, a rare dip below 200k.
Moving onto inflation, DB economists expect the August core PCE deflator (Wednesday) to rise by +0.27% month-on-month, slightly above July’s pace. The report will be accompanied by personal income and spending data, where economists expect gains of +0.5% and +0.6% respectively. Particular attention will be paid to the PCE release given the BEA’s annual benchmark revisions and methodology changes, which could alter the recent inflation profile and affect comparisons with previous months.
Elsewhere in the US, the Conference Board consumer confidence index (tomorrow) is expected to drop to 89.1 from 89.4, while the ISM manufacturing index (Thursday) is expected to rise to 55.0 from 54.6. Remember the S&P composite PMI hit 58.4 last week. We get the ISM services print next week. Wednesday’s final Q2 GDP release will also attract attention as it incorporates benchmark revisions that may reshape perceptions of recent growth trends. As we end the quarter, note that the Atlanta Fed GDPNow is currently tracking at 5.02% for Q3.
Outside the US, European inflation data will dominate the calendar. Preliminary September CPI releases begin with Spain tomorrow, followed by Germany, France and Italy on Wednesday, before the Eurozone aggregate reading on Friday. DB economists expect Eurozone headline HICP inflation to print at 3.75% year-on-year, with core inflation at 2.53%. In Japan, today’s BoJ minutes from the July meeting will be followed by the Q3 Tankan survey and September meeting summary of opinions on Thursday, while economists expect Friday’s Tokyo CPI report to show a further firming in underlying inflation. China’s September PMIs are due on Wednesday, while the RBA announces its latest policy decision tomorrow, where DB economists expect a 25bp rate increase
Here is a day-by-day calendar of events courtesy of DB:
Monday September 28
- Data: US September Dallas Fed manufacturing activity, China August industrial profits, Japan August PPI services
- Central banks: Fed's Barkin speaks, ECB's Lagarde and Pereira speak, BoE’s Ramsden speaks, BoJ minutes of the July meeting
- Earnings: Jefferies
Tuesday September 29
- Data: US September Conference Board consumer confidence index, Dallas Fed services activity, August JOLTS report, July FHFA house price index, UK August net consumer credit, M4, Italy July industrial sales, August PPI, Eurozone September economic confidence, Canada July GDP
- Central banks: Fed's Goolsbee and Williams speak, ECB's Kazimir, Nagel, Escriva and Cipollone speak, BoE’s Taylor speaks, RBA decision
- Earnings: Carnival
Wednesday September 30
- Data: US September ADP report, MNI Chicago PMI, August PCE, personal income, spending, advance goods trade balance, wholesale inventories, China September PMIs, UK September Lloyds Business Barometer, Q2 current account balance, Japan August retail sales, industrial production, housing starts, Germany September CPI, unemployment claims rate, August import price index, retail sales, France September CPI, August PPI, consumer spending, Italy September CPI, consumer confidence, economic sentiment, manufacturing confidence, Australia August CPI
- Central banks: Fed's Barkin, Cook, Goolsbee and Kashkari speak, ECB's Schnabel speaks
- Earnings: Micron, Factset
- Other: G20 Trade Ministerial in Milwaukee (through October 1)
Thursday October 1
- Data: US September ISM index, total vehicles sales, August construction spending, initial jobless claims, Japan Q3 Tankan survey, Italy August unemployment rate, September manufacturing PMI, new car registrations, budget balance, Eurozone August unemployment rate, Canada September manufacturing PMI, Switzerland September CPI
- Central banks: Fed's Barkin, Collins, Schmid, Cook and Logan speak, ECB's Cipollone, Makhlouf, Lagarde, Sleijpen and Nagel speak, BoE's Bailey and Mann speak, BoJ’s summary of opinions from September meeting
- Earnings: Nike
- Other: China National Day holiday (through September 7)
Friday October 2
- Data: US September jobs report, August factory orders, Japan September Tokyo CPI, monetary base, August jobless rate, job-to-applicant ratio, Italy August retail sales, Eurozone September CPI
- Central banks: ECB's Moulin, Cipollone, Vujcic and Nagel speak, BoE’s DMP survey
Finally, lookinat just the US, here is a list of the key economic data releases this week are the core PCE report on Wednesday and the employment report on Friday. There are many speaking engagements with Fed officials this week.
Monday, September 28
- There are no major data releases scheduled.
- 08:15 AM Fed Vice Chair for Supervision Michelle Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will speak about banking supervision and regulation at the 2026 Military Banking Summit in Washington, D.C. Moderated Q&A is expected.
- 01:25 PM Fed Governor Lisa Cook speaks: Fed Governor Lisa Cook will speak about AI and emerging technologies at the 2026 Oakland Tech Week. Speech text is expected.
- 01:30 PM Richmond Fed President Tom Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will participate in a fireside chat at the Working Class Insights Forum in Middleburg, Virginia. Moderated Q&A is expected. On September 24, President Barkin said that “if inflation is not going to come down relatively quickly, then you have to look in the mirror and say inflation looks like it’s been here for a while. So maybe we should do something about it. I think that’s what happened [at the September FOMC meeting].”
Tuesday, September 29
- 09:00 AM Case-Shiller home price index, July (GS +0.3%, consensus +0.2%, last +0.2%)
- 10:00 AM Conference Board consumer confidence, September (GS 89.0, consensus 89.2, last 89.4)
- 10:00 AM JOLTS job openings, August (GS 7,300k, consensus 7,225k, last 7,271k): We estimate that JOLTS job openings were roughly unchanged at 7.3mn in August based on the signal from online measures of job postings from Indeed and LinkUp.
- 11:00 AM Fed Vice Chair for Supervision Michelle Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will deliver virtual opening remarks to the Federal Reserve System Community Bank Cyber Workshop. Speech text is expected.
- 12:40 PM Fed Governor Michael Barr speaks: Fed Governor Michael Barr will speak about the economic outlook at the Detroit Economic Club. Speech text and moderated Q&A with audience are expected. On September 23, Governor Barr noted that “further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion.”
- 01:00 PM Chicago Fed President Austan Goolsbee (FOMC non-voter) speaks: Chicago Fed President Austan Goolsbee will participate in a moderated Q&A at an event organized by the Illinois Manufacturers’ Association. On September 21, President Goolsbee said that “supply shocks have come more frequently, hit harder and lasted longer,” adding that “once supply shocks to inflation become persistent, some of the logic behind ‘looking through’ no longer holds.”
- 02:00 PM New York Fed President John Williams speaks: New York Fed President John Williams will speak at an event organized by the University of Buffalo. Speech text and moderated Q&A are expected. On September 25, President Williams said that the Fed “can’t ignore supply shocks if they have a persistent effect on prices,” adding that it “needs to return inflation to target.”
- 03:00 PM Fed Governor Christopher Waller speaks: Fed Governor Christopher Waller will speak about payments at the 2026 Sibos Conference. Speech text is expected.
Wednesday, September 30
- 08:15 AM ADP employment change, September (GS +75k, consensus +72k, last +38k)
- 08:30 AM Personal income, August (GS +0.5%, consensus +0.5%, last +0.4%): Personal spending, August (GS +0.8%, consensus +0.9%, last +0.2%), Core PCE price index, August (GS +0.27%, consensus +0.3%, last +0.2%), Core PCE price index (YoY), August (GS +3.17%, consensus +3.3%, last +3.3%), PCE price index, August (GS +0.33%, consensus +0.4%, last +0.2%), PCE price index (YoY), August (GS +3.58%, consensus +3.7%, last +3.7%): We estimate that personal income and spending increased by 0.5% and 0.8%, respectively, in August. We estimate that the core PCE price index rose 0.27% in August, corresponding to a year-over-year rate of +3.17% after accounting for our forecast of the revisions that will result from the methodological changes that will be implemented with the August PCE report and will affect the portfolio management, legal services, and computer software and accessories components. Additionally, we expect that the headline PCE price index increased 0.33% and increased 3.58% from a year earlier.
- 08:30 AM GDP, Q2 third release (GS +1.5%, consensus +1.5%, last +1.5%); Personal consumption, Q2 third release (GS +3.4%, consensus +3.4%, last +3.4%): We estimate no revision on net to Q2 GDP growth at +1.5% (quarter-over-quarter annualized), reflecting stronger utilities and personal care details in the QSS offset by softer entertainment and public transportation details. We expect unrevised consumer spending growth at +3.4%. The third release of Q2 GDP will coincide with the 2026 annual update to the National Economic Accounts, which incorporates source data that are more complete than those previously available as well as methodological changes.
- 08:30 AM Advanced goods trade balance, August (GS -$116.0bn, consensus -$115.3bn, last -$118.9bn)
- 01:30 PM Richmond Fed President Tom Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will deliver welcome remarks at the Investing in Rural America Conference hosted by the Federal Reserve Bank of Richmond.
- 03:25 PM Fed Governor Lisa Cook speaks: Fed Governor Lisa Cook will deliver afternoon remarks at the Investing in Rural America Conference hosted by the Federal Reserve Bank of Richmond.
- 05:10 PM Chicago Fed President Austan Goolsbee (FOMC non-voter) speaks: Chicago Fed President Austan Goolsbee will deliver a keynote address at the “Why Consumers and Economists See Different Economies” event in Chicago.
- 06:00 PM Minneapolis Fed President Neel Kashkari (FOMC voter) speaks: Minneapolis Fed President Neel Kashkari will speak in a fireside chat at the Council on Foreign Relations. Moderated and audience Q&A are expected. On September 20, President Kashkari noted that “inflation remains too high and that pressures have broadened beyond the oil-price shock of the Iran war.” He added that “as some of those conflicts go to the background… hopefully disinflation can take over, which will make the Fed’s job a lot easier.”
Thursday, October 1
- 08:30 AM Initial jobless claims, week ended September 26 (GS 200k, consensus 200k, last 197k): Continuing jobless claims, week ended September 19 (consensus 1,730k, last 1,719k)
- 09:05 AM Richmond Fed President Tom Barkin (FOMC non-voter), Boston Fed President Susan Collins (FOMC non-voter) and Kansas City Fed President Jeffrey Schmid (FOMC non-voter) speak: Richmond Fed President Tom Barkin, Boston Fed President Susan Collins and Kansas City Fed President Jeffrey Schmid will speak on a panel about economic trends in rural areas in Asheville, North Carolina. Moderated Q&A is expected. On September 22, President Collins said that she supported the decision to raise the fed funds rate at the September FOMC meeting, adding that “a somewhat more restrictive fed funds rate will help ensure that inflation durably returns to target.” On September 25, President Schmid also noted that he supported the FOMC decision because “we still haven’t fixed the inflation issue.”
- 09:45 AM S&P Global US manufacturing PMI, September final (consensus 57.0, last 57.0)
- 10:00 AM ISM manufacturing index, September (GS 54.6, consensus 55.0, last 54.6): We estimate that the ISM manufacturing index was unchanged at 54.6 in September, reflecting a slight headwind from residual seasonality and a modest decline in regional manufacturing surveys on net—our manufacturing survey tracker declined by 0.6pt to 56.1 in September—that is offset by upward pressure from convergence toward the level implied by other manufacturing surveys (which the ISM index is currently below).
- 10:00 AM Construction spending, August (GS +0.4%, consensus flat, last -0.5%)
- 10:00 AM Fed Governor Christopher Waller speaks: Fed Governor Christopher Waller will speak at the “FRED Con: Navigating Trust, AI and Storytelling in World of Data” event organized by the Federal Reserve Bank of St. Louis. Speech text and moderated Q&A are expected.
- 01:30 PM Fed Vice Chair Philip Jefferson speaks: Fed Vice Chair Philip Jefferson will speak about the US economy and monetary policy at the University of Virginia Darden School of Business. Speech text and moderated Q&A are expected.
- 03:00 PM Fed Vice Chair for Supervision Michelle Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will speak about modernizing financial regulation at an event hosted by the Atlantic Council in Washington, D.C. Speech text and moderated Q&A with audience are expected.
- 03:30 PM Fed Governor Lisa Cook and New York Fed President John Williams speak: New York Fed President John Williams will moderate a discussion with Governor Lisa Cook at a central bank panel hosted by the Federal Reserve Bank of New York.
- 05:00 PM Lightweight motor vehicle sales, September (GS 16.1mn, consensus 16.3mn, last 16.8mn)
- 06:45 PM Dallas Fed President Lorie Logan (FOMC voter) speaks: Dallas Fed President Lorie Logan will speak in a moderated Q&A at the Eleventh District Appreciation Event in Dallas.
Friday, October 2
- 08:30 AM Nonfarm payroll employment, September (GS +80k, consensus +90k, last +162k); Private payroll employment, September (GS +75k, consensus +87k, last +127k); Average hourly earnings (MoM), September (GS +0.2%, consensus +0.3%, last +0.3%); Unemployment rate, September (GS 4.1%, consensus 4.1%, last 4.1%): We estimate nonfarm payrolls increased 80k in September, reflecting a firm signal from alternative data. We estimate average hourly earnings rose 0.2% month-over-month in September, reflecting negative calendar effects. We estimate that the unemployment rate was unchanged at 4.1% in September, reflecting a decline in continuing claims but a relatively high bar for rounding down to 4.0% from an unrounded 4.14% in August.
- 10:00 AM Factory orders, August (GS +0.2%, consensus +0.1%, last +0.8%)
- 10:00 AM Dallas Fed President Lorie Logan (FOMC voter) speaks: Dallas Fed President Lorie Logan will give welcome remarks at the Fifth Annual Workshop on the Macroeconomic Implications of Migration hosted by the Federal Reserve Bank of Dallas. Speech text is expected.
Source: DB, Goldman
